fragmented rails
Inside a country, money is easy: a bank app, a wallet, a card. Across a border it becomes a chain of correspondent banks, nostro accounts, and settlement windows. Each hop adds delay, cost, and a place for the quote to change.
RampPay ........................ A network for money that has to travel
the problem
Inside a country, money is easy: a bank app, a wallet, a card. Across a border it becomes a chain of correspondent banks, nostro accounts, and settlement windows. Each hop adds delay, cost, and a place for the quote to change.
RampPay is that missing product: one layer that takes local money in, moves value on a global settlement network, and pays local money out. People and businesses see a balance and a destination — not crypto, not SWIFT, not a stack of forms.
Collect in the currency people already hold.
Move value once, on a network that does not close at 5pm.
Pay into the account or wallet the recipient actually uses.
the map
Cash, cards, wallets, and bank rails are mature inside a market. Across a border they become a chain of correspondent banks, FX desks, and settlement windows. RampPay sits in the middle as one layer: collect locally, move value globally, pay out locally.
how it holds together
Money enters from the systems people already trust — bank transfer, wallet, or card — in local currency. No new mental model to start a transfer.
Value moves on always-on rails with a quoted rate and a quoted fee. Compliance, liquidity, and FX sit in the product, not as a scavenger hunt after you send.
The other side receives in their local rail — payroll, family, supplier, or merchant account. The infrastructure stays underneath.
rampay api · money movement as a service
Everything the RampPay app does runs on one layer. The API opens that layer to your product: collect in local currency, hold balances, and pay out on local rails, with the rate and fee quoted before every transfer. You ship the experience. Settlement, FX, and compliance run underneath.
The building blocks. Compose what you need.
Price any transfer before it moves: rate, fee, and arrival time in one response.
Collect local currency by bank transfer, wallet, or card, straight into a balance.
Send to bank accounts and wallets on the rail the recipient already uses.
Give each customer a balance they can hold, move, and spend from.
KYC, sanctions screening, and an audit trail inside every call.
An event for every state a transfer passes through: quoted, sent, settled, returned.
for developers
Server-side API keys. Every call is signed and logged.
Ask for a price. The rate and the fee come back before anything moves.
Create the transfer against the quote. Compliance runs inside the call.
A webhook fires when the money lands on the recipient’s rail.
who builds on it
Offer send and receive across borders without building correspondent banking.
Pay in · Pay out · Accounts
Settle merchants and partners abroad in minutes, not on the next banking day.
Quotes · Pay out
Pay contractors and remote teams in the currency they live in.
Pay out · Webhooks
Pay sellers, hosts, and creators wherever they are, on their local rail.
Pay out · Compliance
Pay suppliers with the rate and fee fixed before the goods ship.
Quotes · Pay out
Collect in one currency and pay partners in another, on the same booking.
Pay in · Pay out
Send support home and see the fee before you send.
Pay fees and rent in the country you study in.
Get paid by clients abroad into one balance.
Book flights and hotels from your balance with RAMPAY AI.
API access opens corridor by corridor. Tell us what you are building.
Request API accessin your pocket
The RampPay app keeps your balance, a virtual Visa card, and RAMPAY AI in one place. Ask it to find a flight, book a hotel, send money, or check your spending. It prepares the payment, shows you the price, and waits. Nothing moves until you approve it.
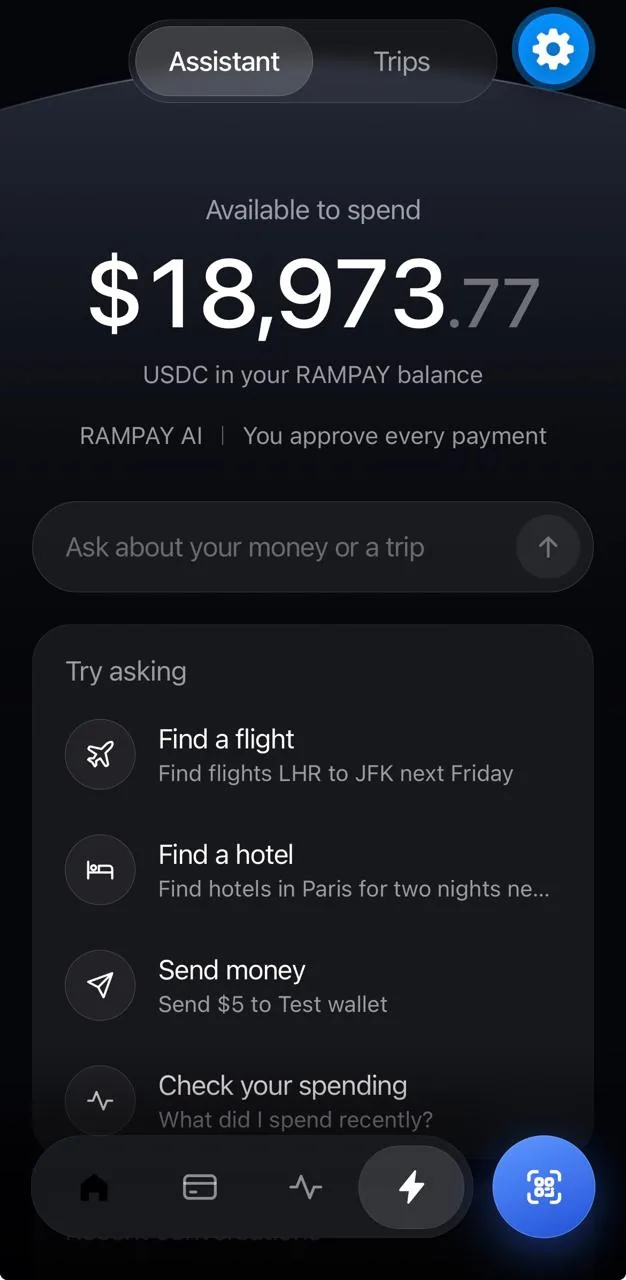
Assistant
Ask about your money or a trip. RAMPAY AI finds the flight, the hotel, or the person to pay, and prepares it. You approve every payment.
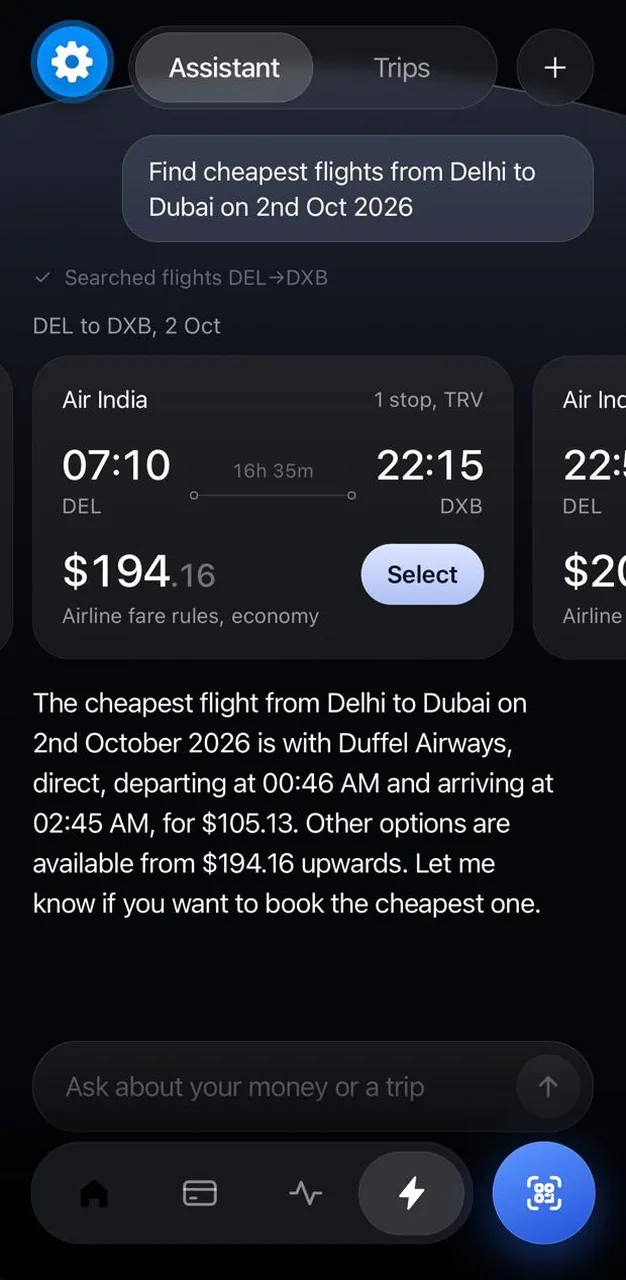
Trips
“Cheapest flights from Delhi to Dubai on 2nd October.” Live fares come back side by side, with the fare rules, and you pay from the same balance.
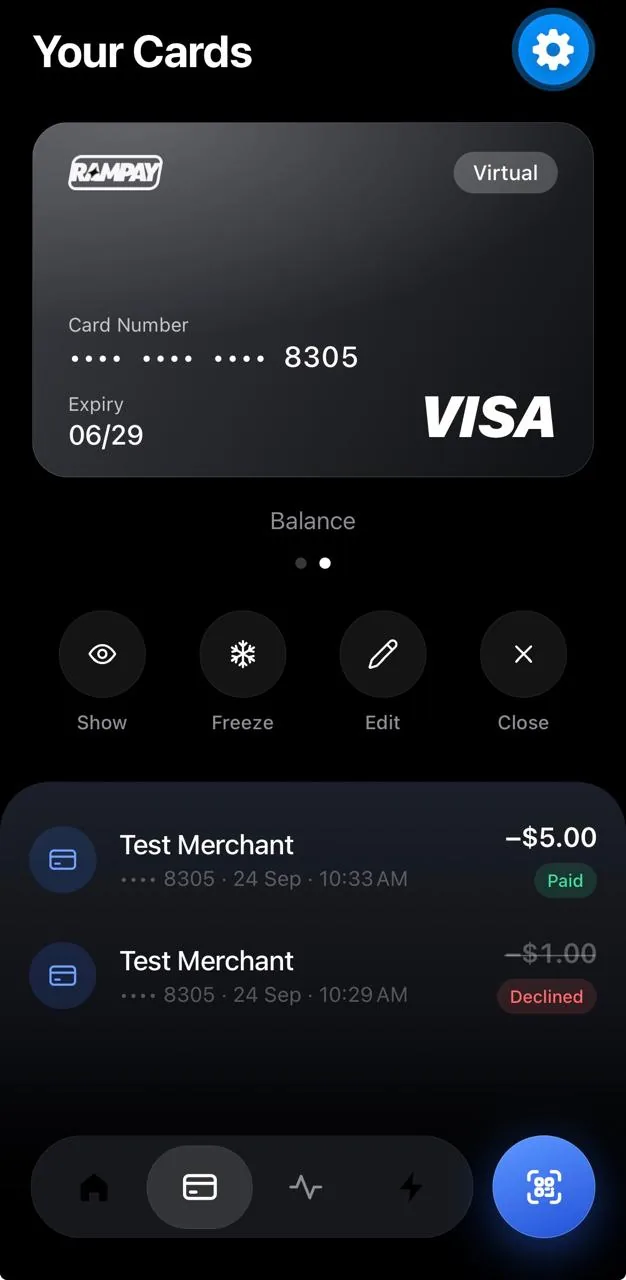
Cards
A virtual Visa card on the same money. Show, freeze, edit, or close it in a tap, and see every charge marked paid or declined.
stablecoin cards
Issue your users a Visa card on their USDC balance, ready in their phone’s wallet. They tap any contactless terminal, RampPay converts at the till, and the merchant is paid in local currency.
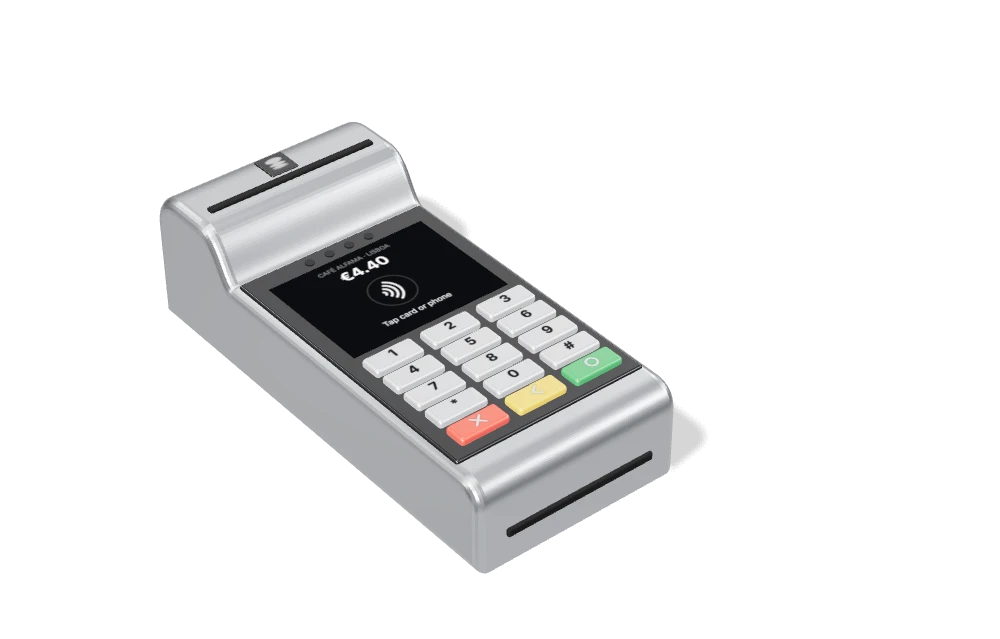
Hold near reader
A Visa card on a USDC balance, in the phone's wallet.
Converted at the till
4.80 USDC becomes €4.40 at the live rate.
Approved
The café is paid in euros. Your user never swapped a thing.
one machine · five stations
From deposit to payout — take it in local, settle it on the rail, pay it out local. Drag to spin, scroll to zoom, click a station to walk the flow.
the crossing
both sides of a payment
RampPay sits between them. Money goes in through the account, wallet, or card someone already uses, moves once on an always-on network, and arrives in the rail the other person already trusts. No new wallet. No chain of banks in the middle.
Corridor launches, product notes, and the next markets we open.
RampPay is a money layer for cross-border value. It collects in local currency, settles on a global network, and pays out in the recipient’s local rail. The settlement machinery stays underneath the product.
Domestic payments already work. Crossing a border still means correspondent banks, opaque FX, and days of waiting. RampPay replaces that chain with one layer so time and cost are quoted up front.
A wire is a message that hops through nostro accounts. A remittance brand is often a fee stack on top of the same hops. RampPay is built as a single product for collection, settlement, and payout — not a new front on the old path.
No. People and businesses interact in local currency. Any on-chain settlement is infrastructure, not a user-facing wallet, seed phrase, or token to manage.
Typical corridors complete in minutes, not business days. Exact timing depends on the local payout rail at the destination.
The quote includes the rate and the fee before send. No surprise deduction after the money is already in flight.
Yes. The RampPay app holds your balance, a virtual Visa card, and RAMPAY AI, an assistant that can find flights and hotels, send money, and check your spending. It prepares each payment and shows the price first. Nothing moves until you approve it.
Yes. The RampPay API gives businesses the same money layer the app runs on: quotes, pay-ins in local currency, customer balances, payouts on local rails, built-in compliance, and webhooks for every transfer state. The rate and fee are quoted before each transfer. API access opens corridor by corridor.
Businesses use the API: fintechs and neobanks, payments companies and PSPs, payroll and employer-of-record providers, marketplaces and creator platforms, import and export, and travel. People use the RampPay app: families sending support home, students abroad, freelancers and remote workers, and travellers.
Anyone whose money has to travel: families, operators paying global teams or suppliers, and platforms that need collection and payout without rebuilding correspondent banking.
RampPay works with licensed banking and payout partners, and builds KYC, screening, and auditability into the layer rather than bolting them on later.
We are opening corridors in batches. Follow RampPay on LinkedIn or X for launch news and the next markets we open.